How to Structure Treasury and Manage Currencies in North America
A practical guide to identifying exposures in USD, CAD, and MXN, organizing cash flows, and deciding when hedging foreign exchange risk may make sense.
Operating across the United States, Canada, and Mexico can involve receiving, paying, or borrowing in United States dollars (USD), Canadian dollars (CAD), and Mexican pesos (MXN). If receipts and payments do not align in timing or currency, exchange-rate movements can affect margins and cash forecasts even when business volumes remain unchanged.
Managing this risk is not about predicting the market or hedging every movement. The first step is to understand what exposure the company has, when it will materialize, and how it could affect liquidity and results. Treasury can then establish rules proportionate to the organization’s size, operations, and ability to maintain controls.
Distinguish the three types of foreign exchange risk
Transaction exposure arises when a foreign-currency receipt, payment, debt, or other obligation exists and the exchange rate may change before it is settled. This exposure is most directly linked to cash flow. For example, a company whose functional currency is USD and that will collect an invoice in MXN in several weeks will receive a dollar amount that depends on the exchange rate in effect when the payment is converted.
Translation exposure affects the presentation of financial statements. It can arise when consolidating a subsidiary that keeps its accounts in CAD or MXN into the statements of a parent whose presentation currency is USD. Valuation changes can alter accounting figures even when no equivalent cash movement has occurred.
Economic exposure is longer-term: it reflects how sustained currency movements may affect competitiveness, prices, and future cash flows. A company can have this exposure even without an outstanding invoice in the currency that is moving—for example, if its costs or competitors depend on that currency.
These effects should not be confused. An accounting loss from translation does not necessarily mean an immediate cash outflow, whereas an outstanding invoice can change the cash received or paid. Economic exposure, in turn, is harder to measure and is not necessarily resolved by a short-term hedge.
Editorial illustration · Edition Business
Build a currency and maturity position map
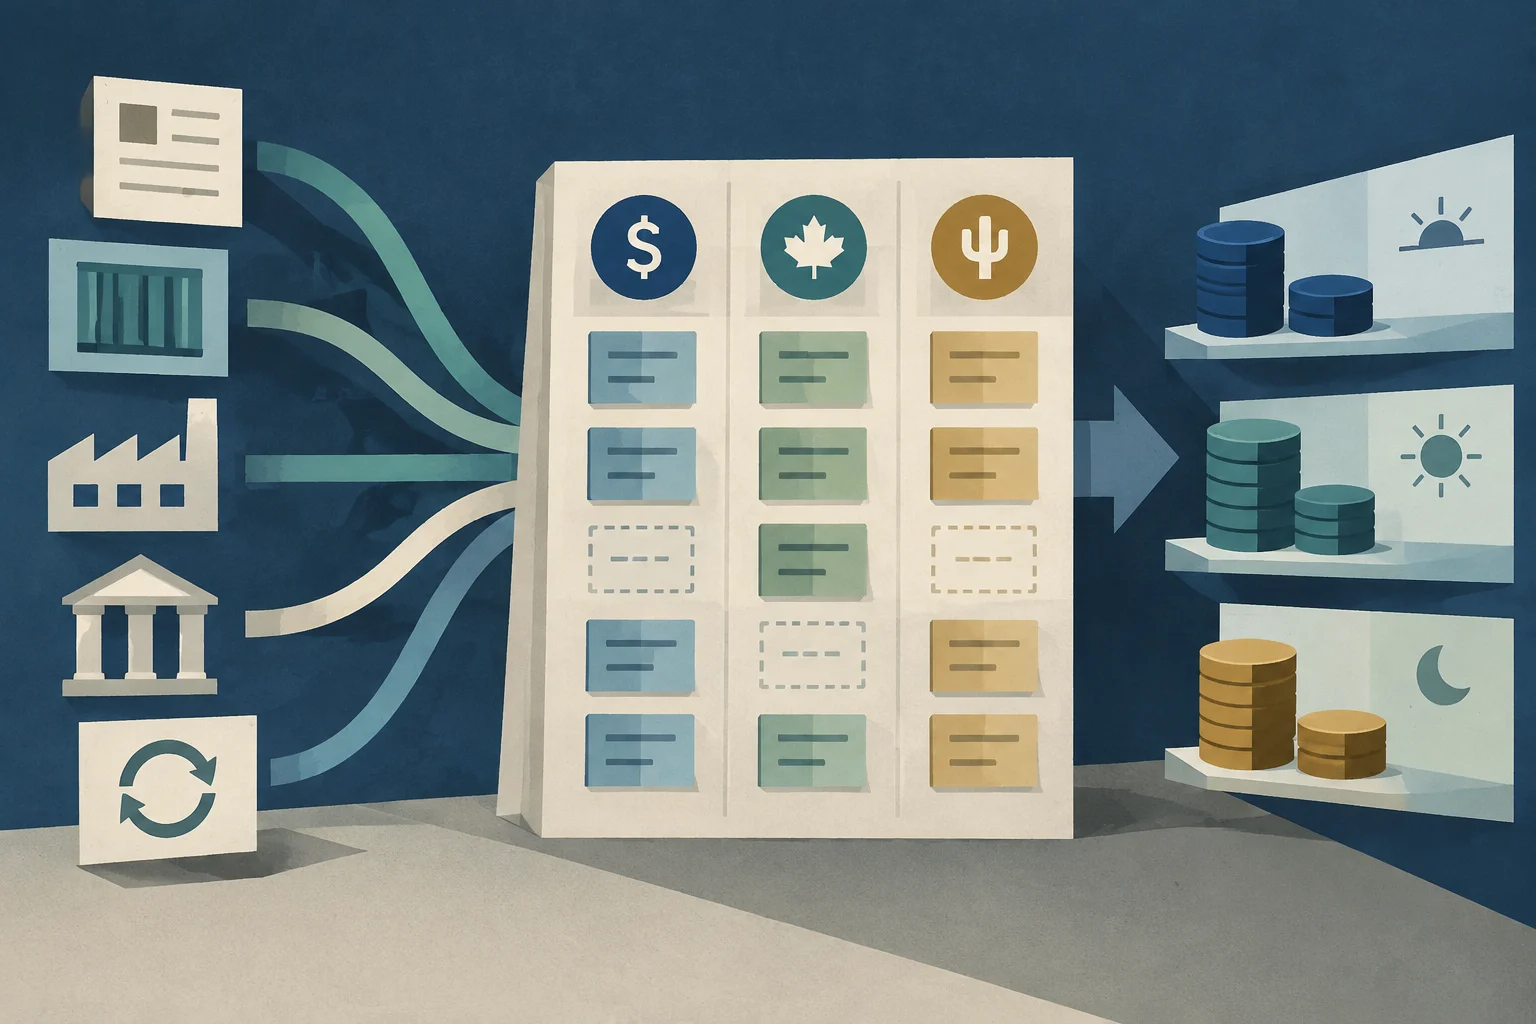
Treasury needs a shared view of expected and confirmed cash flows. At a minimum, the inventory should include accounts receivable, accounts payable, loans, significant purchase orders, and recurring commitments denominated in a currency other than the functional currency. For each position, it is useful to record:
Currency and nominal amount.
Expected receipt or payment date, or maturity range if the date is not known precisely.
Degree of certainty: confirmed invoice, order, sales forecast, or another estimate.
Responsible entity and the bank account from which settlement will be made.
Budgeted exchange rate and the approximate effect of a movement, when that information is available.
Next, group cash flows by currency and period. For example, the company can compare expected USD receipts with USD payments over the same horizon, then repeat the exercise for CAD and MXN. The net position in each currency is the difference between comparable inflows and outflows; calculating it by maturity helps avoid treating flows on different dates as offsetting one another.
A simple template could show receipts, payments, and the net balance in USD, CAD, and MXN for each period. There is no need to start with a complex tool: what matters is using a consistent method, identifying data sources, and assigning responsibility for updating changes. Forecasts should be distinguished from obligations already contracted, because they do not have the same degree of certainty.
Organize receipts, payments, and cash balances
Before turning to financial instruments, the company can review its operations. Where commercially feasible, invoicing and paying in the same currency can reduce unnecessary conversions. It is also helpful to consider whether customer and supplier due dates can be better coordinated, and to maintain foreign-currency balances only when they serve specific operational needs and are supported by appropriate internal controls.
These measures do not eliminate risk. Receiving and paying in USD, for example, may offset part of the exposure if the amounts and dates are close; if payments fall due earlier, the company may still need to finance the timing gap. Similarly, keeping a foreign-currency balance can facilitate future payments, but its value expressed in the functional currency can also fluctuate.
The cash forecast should show both the amount and timing of flows. A monthly total may conceal that payments fall due before receipts, or that an apparently balanced position is concentrated on different dates. For companies operating in several countries, it is useful to separate the liquidity needed for operations from the exposure being managed financially.
Define a hedging framework before executing transactions
If the company decides to use hedges, it needs criteria agreed in advance. An internal policy can specify which exposures are hedged, the required level of certainty, who authorizes transactions, which instruments are permitted, and how they are recorded and reviewed. It can also set limits by currency, period, or counterparty, adapted to the company’s structure and controls.
Market tools include forward contracts, which allow an exchange rate to be set now for a future transaction under agreed terms. They can provide greater predictability about the amount in the functional currency, but they entail commitments, and their terms, costs, flexibility, and accounting treatment should be understood before use. A hedge also does not guarantee the best possible rate or eliminate every difference between the forecast and the cash flow ultimately realized.
For this reason, a hedge’s size and maturity should correspond to an identifiable exposure. Hedging an uncertain forecast can create a mismatched position if the sale does not go ahead or changes date. Conversely, hedging only confirmed invoices can leave some volatility in future cash flows unmanaged. The policy should explicitly reflect how this difference is handled, without assuming that one rule works for every company.
Editorial illustration · Edition Business
Improve visibility with data and automation
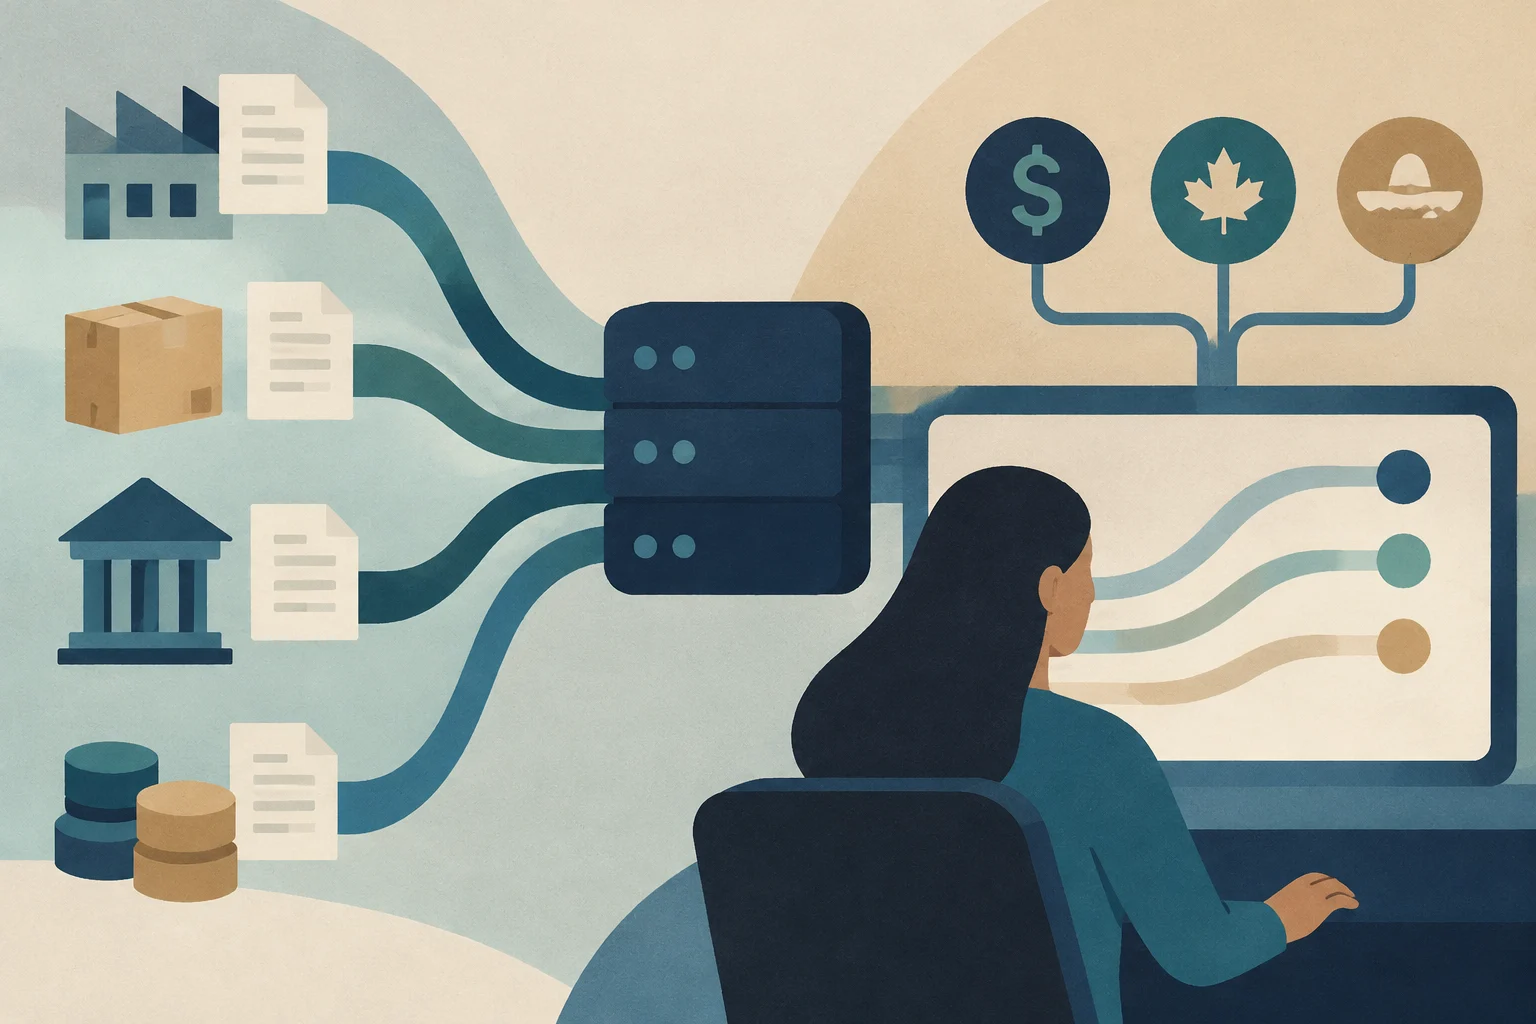
Automation can bring together information from invoicing, accounts payable, banks, and accounting systems to keep the exposure map up to date. Its usefulness depends on more than technology: it requires comparable data, consistent currency codes, reliable dates, and clear ownership. If sales and purchasing teams do not communicate changes to orders or terms, an up-to-date dashboard can still show an inaccurate forecast.
A control process can include periodic reconciliation between forecast and executed positions, review of overdue invoices, and comparison of budgeted and applied exchange rates. It is also useful to document exceptions, hedging decisions, and authorizations so that finance can explain variances and verify that internal limits were respected.
For a small or medium-sized business, the initial goal can be modest: consolidate cash flows by currency and date in a reliable source and assign one person to review them periodically. As volume and complexity increase, the company can consider more integrated tools. Automation supports consistency and speed, but it does not replace judgment about which risks to take or the control of transactions.
A repeatable management cycle
An operating framework can be organized as a continuous cycle:
Identify receipts, payments, debts, and other positions in USD, CAD, and MXN.
Classify each exposure as transaction, translation, or economic, and separate confirmed amounts from forecasts.
Measure net balances by currency and maturity, together with liquidity needs.
Decide which portion to manage through operational adjustments and which portion, if appropriate, through authorized hedges.
Execute and record decisions with assigned responsibilities, limits, and documentation.
Review positions, maturities, and differences between forecasts and actual outcomes to adjust the process.
Review frequency will depend on transaction volume, cash-flow volatility, and the company’s ability to update its data. A company with few international payments may need a simpler process than one with numerous invoices and subsidiaries; in both cases, the discipline of identifying and reviewing exposures is more important than the sophistication of the system.
Scope and limitations
Foreign exchange management can help reduce uncertainty about certain cash flows and improve planning, but it does not eliminate business risk or guarantee financial outcomes. Available strategies and instruments depend on contractual terms, jurisdiction, financial providers, and applicable accounting and tax rules. Because the reference material does not specify the company’s country of incorporation or the relevant regulatory framework, it is not possible here to establish specific legal, tax, or accounting requirements for the United States, Canada, or Mexico.
The central operational decision is to maintain a reliable picture of how much is owed or expected to be received in each currency and on what date. On that basis, the company can distinguish liquidity mismatches from accounting changes and assess, under a defined policy, which exposure it accepts and which it wants to limit.
Defining what is certified, how the billable amount is calculated, and when payment is due helps prevent duplicate charges, measurement disputes, and cash-flow pressures on construction projects.
A reliable estimate adds employer costs and other expenses to wages, divides the total by the hours actually spent on productive work, and adjusts the result to the productivity of each work item and its indirect costs.
A practical guide to turning a small business’s records into an income statement, a balance sheet, and a historical statement of cash flows—and checking that the figures tie together.