Guide to Choosing a Business Structure in the U.S.: Sole Proprietorship, Partnership, LLC, S Corp, and C Corp
Discover how to distinguish between legal entity and tax treatment to select the optimal structure in the U.S. We analyze liability, taxes, and costs for each option.
One of the biggest confusions for entrepreneurs in the United States is treating the LLC (Limited Liability Company) and the S Corporation as mutually exclusive options. In reality, they are concepts that operate on different planes: the LLC is a legal entity created under state law, while the S Corp is a federal tax classification available to eligible entities.
The IRS (Internal Revenue Service) establishes that the federal classification of an LLC depends on its owners and the elections it makes. A single-member LLC is generally considered disregarded for federal tax purposes, unless it elects corporate treatment. On the other hand, an LLC with two or more members usually has a default partnership treatment.
To make an informed decision, it is fundamental to answer two key questions:
What legal entity will own and operate the business?
How will that entity and its owners report and pay taxes?
Analysis of the Main Legal Forms
The Small Business Administration (SBA) describes the main options and their trade-offs. Below, the characteristics of each structure are detailed.
Sole Proprietorship
This is the simplest form of business, where one person operates without a separate legal entity. The SBA notes that anyone who engages in commercial activities without registering as another type of business is generally treated as a sole proprietor.
Advantages: Quick start, no initial formation costs, and minimal bureaucracy.
Disadvantages: There is no separation between personal and business assets. If the business owes money, the owner's personal assets may be exposed. Additionally, the owner pays the self-employment tax of 15.3% on the entirety of net earnings.
Partnership
This involves two or more owners. Variants exist such as general partnerships, limited partnerships, and limited liability partnerships, each with different levels of legal protection.
Advantages: Allows sharing the financial and operational burden.
Disadvantages: In a general partnership, personal liability is a major concern. Taxation requires an informational return from the partnership and Schedule K-1 reports for each partner, although the partnership generally does not pay federal income tax itself.
LLC (Limited Liability Company)
Formed under state law, its owners are called members. It offers limited liability and flexibility in management and federal tax classification.
Advantages: Protects personal assets from business debts and allows choosing how to be taxed (as a sole proprietor, partnership, or corporation).
Disadvantages: Requires compliance with state requirements, such as filing formation documents (for example, Articles of Organization in California or Certificate of Formation in Texas) and maintaining an operating agreement.
Corporations
These are separate legal entities with shareholders. They offer limited liability and a structure to issue stock and raise capital.
Advantages: Ideal for companies seeking external investment or going public. They allow unlimited growth through the sale of stock.
Disadvantages: Require more extensive formal governance, including bylaws, regular meetings, and filing government reports.
Editorial illustration · Edition Business
The Tax Impact: S Corp vs. C Corp
The choice between an S Corporation and a C Corporation has profound tax implications.
C Corporation: Double Taxation
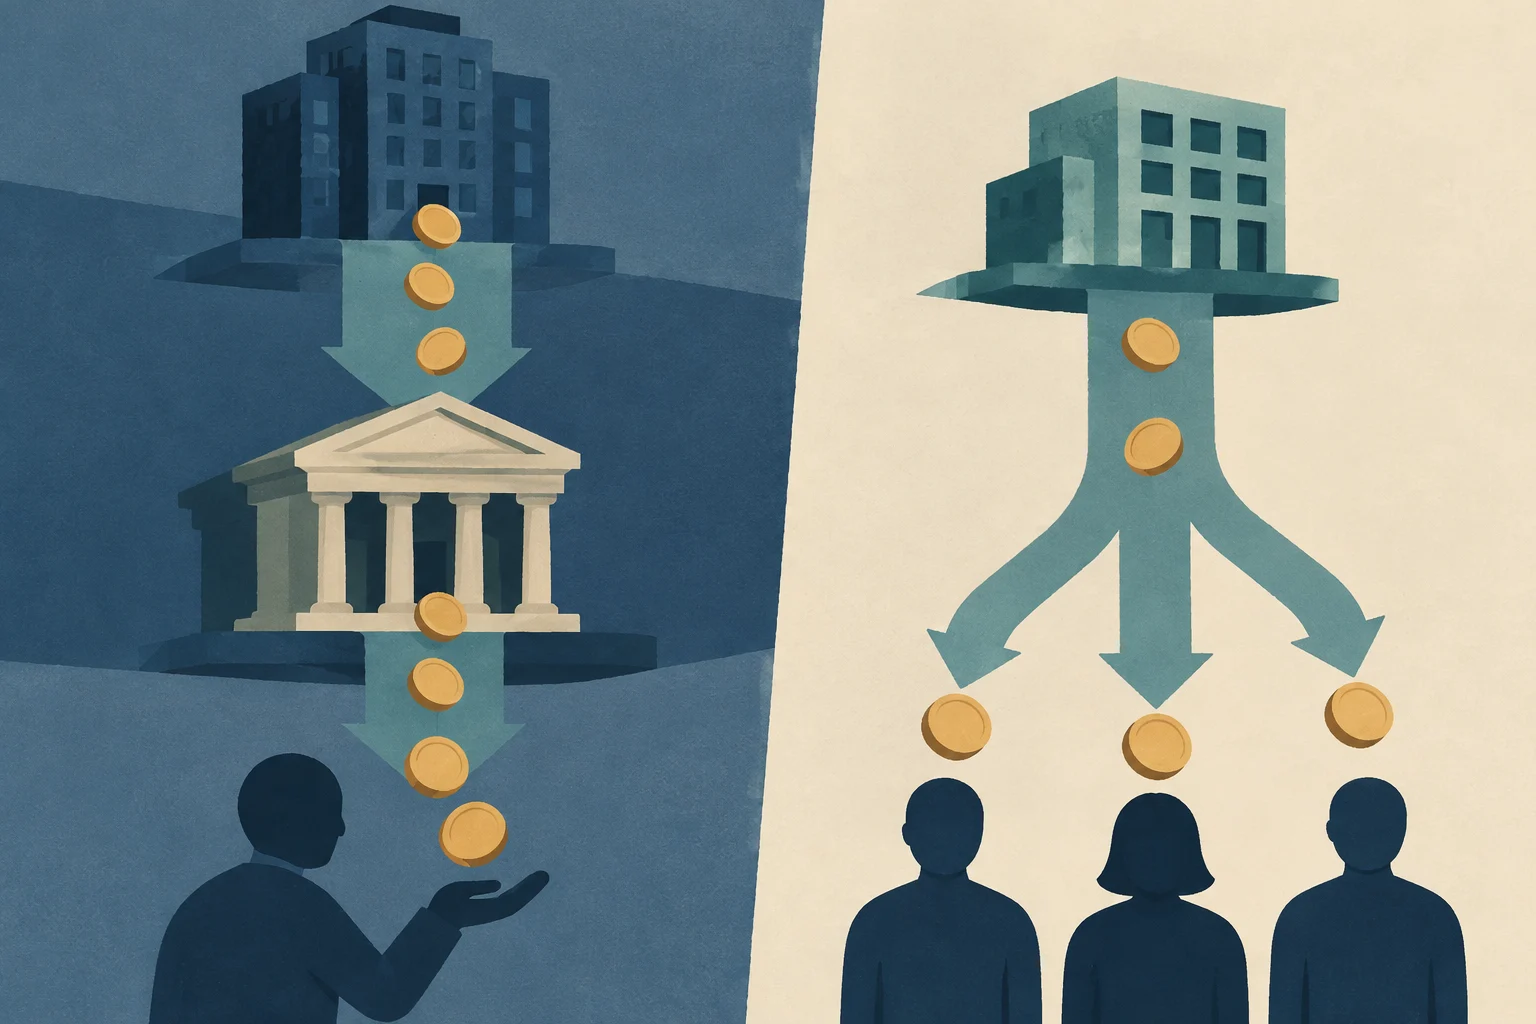
C Corps are subject to double taxation. First, the corporation pays the federal corporate income tax (currently at 21%). Then, shareholders pay personal income tax when earnings are distributed as dividends. This does not mean that every dollar is taxed twice, but rather that there are two levels of taxation.
S Corporation: The Pass-Through Advantage
S Corp treatment is a federal tax classification where income, deductions, and losses pass directly to shareholders for federal tax purposes. This avoids corporate double taxation.
A key advantage of the S Corp is the possibility to avoid part of the self-employment tax on profit distributions, provided that the owner-shareholder receives reasonable compensation for their services. The IRS requires that a reasonable salary be paid before making non-salary distributions.
Criteria for the Final Decision
There is no universally "best" structure; the choice depends on the nature, size, and goals of the business. Experts recommend evaluating the following factors:
Liability: Do you need to protect your personal assets? If so, an LLC or Corporation is preferable to a Sole Proprietorship.
Taxes: Are you looking to minimize the tax burden? For profitable owner-operated businesses, the S Corp is often advantageous due to the reduction in self-employment tax on distributions.
Financing: Do you plan to raise capital from external investors or go public? The C Corp is the standard structure for this purpose.
Administrative Complexity: Are you willing to comply with governance requirements and annual reports? Corporations and LLCs require more bureaucracy than simple partnerships.
When to Consider a Change of Structure
It is possible that a structure that works at the start of the business is not optimal as it grows. For example, a single-member LLC can elect to be taxed as an S Corp to save on self-employment taxes. However, this change requires meeting the S Corp eligibility requirements, such as having no more than 100 shareholders and only one class of stock.
Before making any change, it is crucial to consult with a qualified attorney or tax professional to evaluate the specific implications of your situation. Rules vary by state, and tax consequences can be significant.
This guide offers an overview of business structures in the U.S. For specific decisions, it is always recommended to seek qualified professional advice.
Anticipate increases in construction activity with a practical checklist for reviewing forecasts, bottlenecks, materials, personnel, equipment, suppliers, quality, and safety before expanding capacity.
Learn how to verify a VAT identification number in the European Commission’s VIES system to correctly apply the VAT exemption to intra-Community transactions and avoid tax risks.
Learn to use free official tools to investigate prior art, verify inventions and analyze patent documents. This guide explains how to formulate effective searches in Espacenet, PATENTSCOPE and national registers such as INVENES and DEPATISnet.